

In our last article, we discussed common duplex insurance mistakes, but now it’s time to turn our attention to seasonal duplexes.
With the US vacation rental market worth more than $15 billion, you’d think owners would ensure their vacation rentals are adequately protected. That’s not the case, however. It’s common for these types of properties to be underinsured.
Owning a seasonal duplex rental property is an exciting investment, but protecting it when it sits empty can be tricky. That’s where seasonal duplex insurance comes in, offering the coverage you need for risks that standard homeowners policies often overlook.
Remember, the importance of duplex property coverage cannot be stressed enough.
So, if you’re renting out your property or just using it for vacations, this guide will walk you through everything you need to know about insuring your duplex in 2025 so you can safeguard your property and enjoy peace of mind year-round.
Lastly, if you’re already set on getting insurance for your property but don’t know where to start, consider reading our duplex insurance review guide.
Short Summary
- Seasonal duplex insurance provides coverage for properties occupied only during specific seasons, such as vacation homes or cabins.
- Common risks for seasonal properties include vandalism, weather damage, wildlife intrusions, and fire hazards.
- Specialized insurance protects against risks that standard homeowners policies often don’t cover, especially when the property is unoccupied.
- Key coverage options include property damage protection, liability coverage, loss of rental income insurance, and personal property coverage.
- Factors affecting premiums include location, property age, construction materials, and security features.
Seasonal Duplex Insurance: What You Need to Know
Seasonal duplex insurance is designed for properties occupied only during certain seasons. This can include vacation homes, cottages, or cabins that are used primarily during summer or winter months and left unoccupied for the rest of the year.
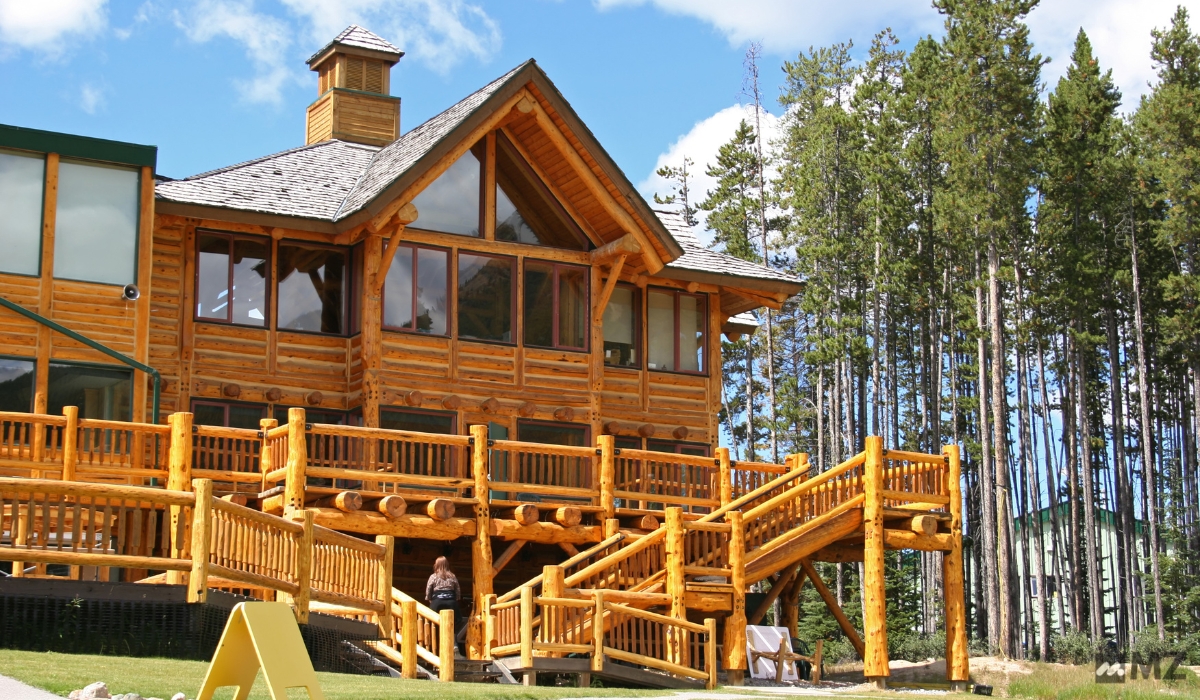
Since these types of property are unoccupied for long periods, they face risks like the following:
- Vandalism and Theft
- Weather Damage
- Wildlife Intrusions
- Fire Hazards
That’s where specialized insurance for seasonal properties steps in, offering the protection you can’t get from a standard homeowners policy. Many owners assume their standard homeowner’s policy has them covered. Unfortunately, it usually doesn’t.
Standard homeowners insurance policies often do not provide adequate coverage for seasonal properties. What specialized coverage can do for you is ensure that your seasonal property is protected against the risks (like the ones enumerated above) it faces when unoccupied.
Common Misconceptions About Standard Homeowners Insurance For Seasonal Properties
Myth: My standard homeowners insurance covers my seasonal property year-round.
Fact: Most standard policies have limitations on coverage for properties that are unoccupied for extended periods.
Myth: I don’t need to inform my insurer if I rent out my seasonal property occasionally.
Fact: Rental activity can change your property’s risk profile, and failing to disclose it can result in denied claims.
Myth: Seasonal properties are not at risk of damage when unoccupied.
Fact: Seasonal properties are at higher risk of damage due to extended vacancy.
Key Coverage Options For Your Seasonal Duplex
There are several coverage options to consider when insuring your seasonal duplex. Each one provides a layer of protection that you won’t find in standard insurance.
Here are several:
Property Damage Protection
Fire, theft, and weather-related incidents can happen when you least expect it. With property damage protection, you’re covered against these events, even if you’re not around to respond right away.
Liability Coverage for Guest Injuries
If you rent out your duplex or invite guests to stay, liability coverage protects you from potential lawsuits or medical costs in case someone is injured on your property or suffers any personal injury.
For vacation rentals, this is a must-have, as guests’ injuries or property damage can occur when renting to strangers.
Loss of Rental Income Insurance
If an insured event makes your duplex unlivable, loss of rental income insurance helps recover the income you would have earned during that time. This is a crucial safety net for those who rely on seasonal rental income.
Personal Property Coverage
Remember to include personal property coverage for your furnishings, equipment and other personal belongings. We always advise owners to do a thorough inventory. You’d be surprised how quickly the value of furniture, appliances, and decor adds up in a fully furnished rental.
Additional Living Expenses Coverage
Did something happen to your duplex, and you need to live elsewhere temporarily? Additional living expenses coverage can cover the cost of accommodations, meals, and other daily expenses.
This is particularly important if a covered event like a fire or major storm displaces you.
Understanding Policy Limits and Deductibles
It’s essential to review the limits and deductibles of your policy. Higher limits mean better protection, but they also come with higher premiums. Likewise, a higher deductible can lower your monthly costs but requires more out-of-pocket if a claim is made.
Finding that sweet spot between your budget and your coverage needs can be a challenge, but it can be done.
Evaluating Customer Service And Claims Process Reputation
Not all insurance companies offer the same level of customer service or efficiency in processing claims. Look for providers with strong reputations for handling claims promptly and fairly.
This ensures that if something does go wrong, the process of getting your life back on track will be as smooth as possible.
Factors Affecting Your Seasonal Duplex Insurance Premiums
Several factors influence the cost of your seasonal duplex insurance. Here are some of them:
Location And Climate Considerations
Where your duplex is situated plays a huge role in determining your premiums. Beachfront properties in hurricane-prone areas face significantly higher rates than similar duplexes in less risky locations.
Coastal duplex insurance may include additional coverage for storm damage or flooding. Climate change is also increasingly factoring into insurers’ calculations. For example, a client’s mountain cabin saw a premium hike due to increased wildfire risk in the area.
Property Age And Construction Materials
The age and build of your duplex matter more than you might think. Older properties often come with higher premiums due to outdated wiring or plumbing systems. Fire-resistant materials can also lead to lower rates in some areas.
For example, a duplex with a reinforced roof or updated electrical systems may qualify for lower rates. Duplex roof coverage and plumbing insurance can also be factors to consider, as older systems may require extra protection.
Security Features And Risk Mitigation Measures
Security systems like smart home technology or fire alarms can significantly lower your insurance premiums. Insurers see these as risk mitigation measures, making your duplex less likely to experience theft, vandalism, or fire.
Installing cameras or a burglar alarm not only protects your property but can also lead to discounts, helping you save on your vacation home insurance. Installing a monitored security system and impact-resistant windows can save you around 15% on your policy.
Occupancy Patterns And Rental Usage
How often your duplex is occupied and whether you rent it out affect your rates. Properties left vacant for long periods may face higher premiums due to increased risk of undetected damage or break-ins.
Short-term rentals might also impact your rates, as insurers view the frequent turnover of occupants as an added risk.
Properties with a more frequent turnover of tenants may carry higher liability risks, making short-term rental insurance a necessity.