

Did you know that more than 2 million rental properties in the U.S. are duplexes? That’s a lot of potential for unexpected disasters like fires, burst pipes, or tenant liability claims.
As a duplex owner, you’re juggling two units, two sets of tenants, and double the risk. What happens when disaster strikes and you must file a duplex landlord insurance claim?
The process can be confusing and overwhelming, especially if you’re dealing with separate insurance for each unit in a duplex or landlord insurance for an owner-occupied duplex.
From our experience, many landlords think that filing an insurance claim is a headache.
With that said, this article provides a clear, step-by-step guide on how to file a duplex landlord insurance claim. We want you to receive the maximum coverage you deserve and get your property back on track with minimal stress.
Short Summary
- Duplex landlord insurance coverage protects duplex owners from costs related to property damage, liability, and lost rent.
- Duplex landlord insurance coverage may exclude earthquakes, floods, pests, and wear and tear. Review your policy for limitations and consider extra coverage.
- Check your policy documents (mailed or online), or contact your insurance agent to find your policy number.
- ACV factors in depreciation, paying current market value. Replacement cost covers the cost of new replacements.
- Gather photos, repair records, tenant communication, police reports (if applicable), contractor estimates, and inspection reports.
- Here’s a quick run-down on how to file a claim. Contact your insurer, take emergency measures, complete the claim form/s, document communication, and submit the claim (or by paper) digitally as required.
- To Maximize your insurance claim settlement, assess the damage accurately, work effectively with adjusters, avoid common mistakes, and negotiate strategically.
- Track your claim, handle adjuster visits, address new damage, know the appeals process, maintain records, and understand the reimbursement timeline.
What Is Duplex Landlord Insurance Coverage?
Duplex landlord insurance is a specialized type of insurance designed to protect owners of duplex properties. It helps cover the costs associated with property damage, liability claims, and loss of rental income. This coverage is essential for landlords as it safeguards their investment and provides financial protection against unexpected events arising from owning and renting out a duplex.
Types Of Incidents Covered By Typical Landlord Policies
- Fire damage: Including damage from smoke and efforts to extinguish the fire.
- Vandalism and malicious mischief: Intentional damage caused by others.
- Weather-related damage: Such as damage from wind, hail, or lightning.
- Water damage: Often from burst pipes, leaks, or appliance malfunctions (usually excluding floods).
- Liability claims: Covers legal costs and settlements if a tenant or guest is injured on the property.
- Loss of rental income: Provides compensation if the property becomes uninhabitable due to a covered incident.
Common Exclusions And Limitations To Watch For:
While landlord insurance offers broad protection, it’s important to be aware of common exclusions. These may include damage from earthquakes, floods, pests, or wear and tear. Policies may also limit coverage amounts, especially for high-value items or specific types of damage.
It’s crucial to review your policy carefully to understand its limitations and consider purchasing additional coverage if needed.
How To Quickly Locate Your Policy Number And Coverage Details:
Your policy number and coverage details are typically found on your insurance policy documents. These documents are usually mailed to you after purchasing the policy. You can also often access them online through your insurance company’s website or by contacting your insurance agent directly. Keep these documents in a safe and easily accessible place for quick reference.
Difference Between Actual Cash Value Vs. Replacement Cost Coverage:
- Actual Cash Value (ACV): This type of coverage factors in depreciation, meaning it pays for the current market value of the damaged property, not the cost to replace it with new items. For example, if your roof is damaged, ACV will consider its age and wear and tear, resulting in a lower payout than replacement cost.
- Replacement Cost Coverage: This coverage pays for the full cost of replacing damaged property with new items, regardless of depreciation. Using the roof example, replacement cost coverage would pay for a brand-new roof, even if the damaged one was old. While this option typically has higher premiums, it provides more comprehensive financial protection in the event of a claim.
Understanding Deductibles And Their Impact On Claims:
A deductible is the amount you pay out-of-pocket before your insurance coverage kicks in. For example, if your deductible is $1,000 and you have $5,000 in covered damage, you’ll pay the first $1,000, and your insurance will cover the remaining $4,000.
Choosing a higher deductible can lower your premium costs, but it also means you’ll pay more upfront in the event of a claim.
Essential Documentation Needed Before Filing Your Claim
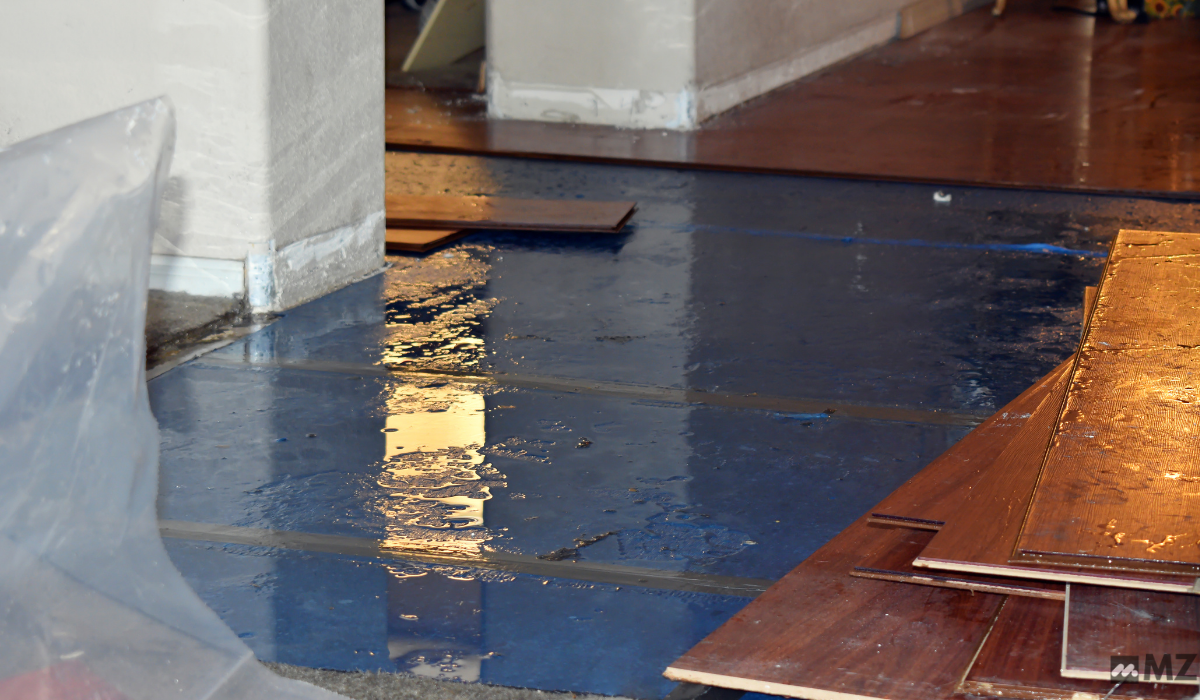
Before you pick up the phone, call your insurance company and gather the right documentation. This will streamline the claims process and help you get the most out of your coverage.
Comprehensive Property Damage Photographs
Thorough photographic evidence is crucial. Capture clear images of all damaged areas from multiple angles. Include close-ups to show the extent of the damage. If possible, take photos before and after any temporary repairs to document the initial condition.
Dated photos provide a visual record for your insurer and can help support your claim.
Maintenance And Repair Records
Keep detailed records of all past maintenance and repairs. This demonstrates that you’ve taken pro